Importance of Budget vs. Actual Reports
Budget vs. actual reports provide nonprofits with a structured comparison between planned financial activity and actual performance. They matter because they help leaders track progress, identify discrepancies, and make timely adjustments. For nonprofits in social innovation and international development, these reports are especially critical in managing donor funds, where transparency and accountability are non-negotiable. Boards, donors, and management teams rely on them to ensure that resources are being used as intended and that the organization remains financially healthy throughout the year.
Definition and Features
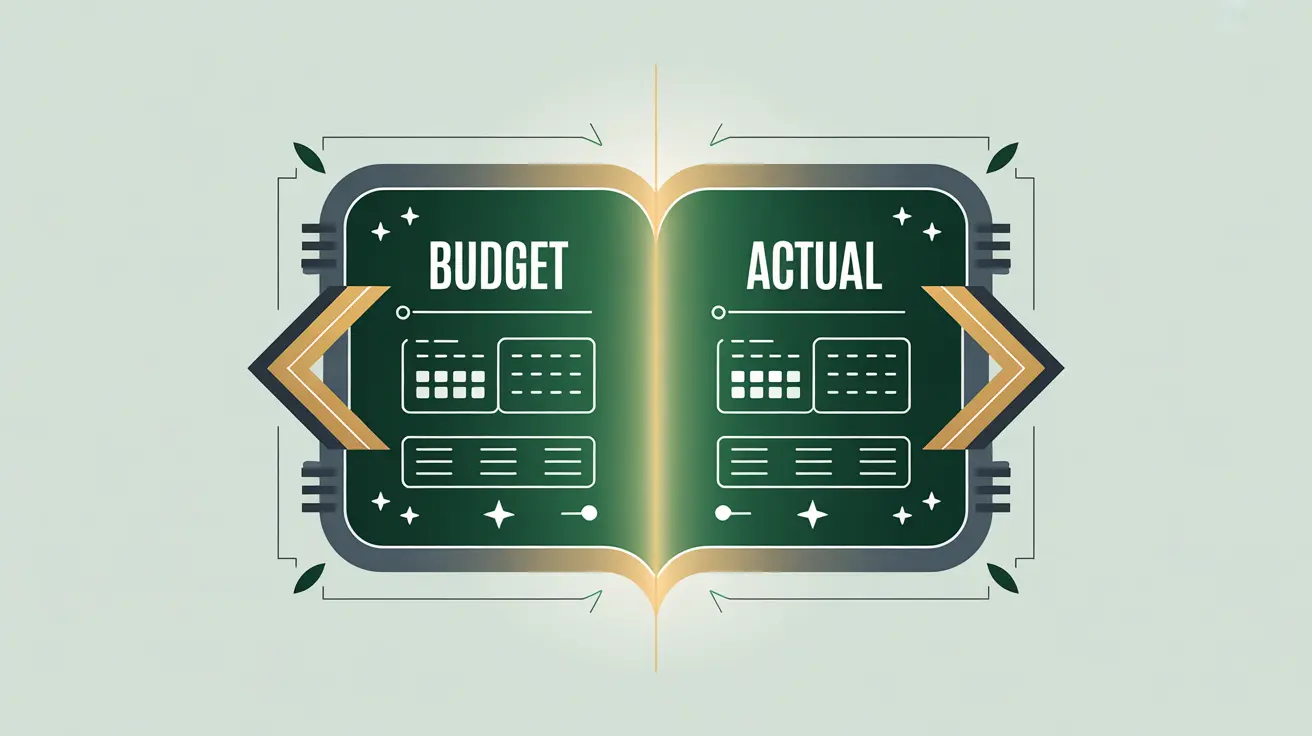
A budget vs. actual report is defined as a financial statement that compares budgeted revenues and expenses to actual results for a given period. Key features include:
- Comparison Columns: budgeted figures, actual results, and variance.
- Timeframes: monthly, quarterly, or annual snapshots.
- Flexibility: can be prepared for the whole organization, specific programs, or grants.
- Decision Support: highlights areas requiring corrective action or reallocation.
These reports differ from variance analysis, which digs deeper into explanations, by serving as the baseline comparison that highlights where variances exist.
How This Works in Practice
In practice, nonprofits generate budget vs. actual reports regularly, often monthly, from their accounting systems. For example, if a literacy program budgeted $50,000 for materials but only $30,000 has been spent halfway through the year, the report reveals both savings and whether delivery targets are still on track. Finance teams share these reports with program managers to guide implementation decisions, while leadership and boards use them to monitor overall financial performance. Donors frequently request grant-specific budget vs. actual reports to verify compliance with funding agreements.
Implications for Social Innovation
For nonprofits in social innovation and international development, budget vs. actual reports are central to fostering accountability and agility. Transparent reporting reduces information asymmetry by giving stakeholders a clear view of financial performance against expectations. Donors appreciate the clarity, as it reassures them that funds are managed responsibly. Internally, these reports empower program managers to adjust activities and spending in real time, ensuring resources are aligned with impact goals. By embedding budget vs. actual reporting into financial management, nonprofits strengthen credibility, improve responsiveness, and ensure mission-driven work is supported by sound fiscal discipline.